Insurance & claimsGuide 4 of 5
Does homeowners insurance cover foundation repair?
From Below the Sill · belowthesill.com/insurance/foundation-damage/
Short answer
Only when a covered event caused the damage, such as a vehicle hitting the wall or a sudden plumbing leak. Most foundation problems come from slow processes, like settlement, soil that shrinks or swells, or poor drainage over years, and those are usually excluded.
On this page
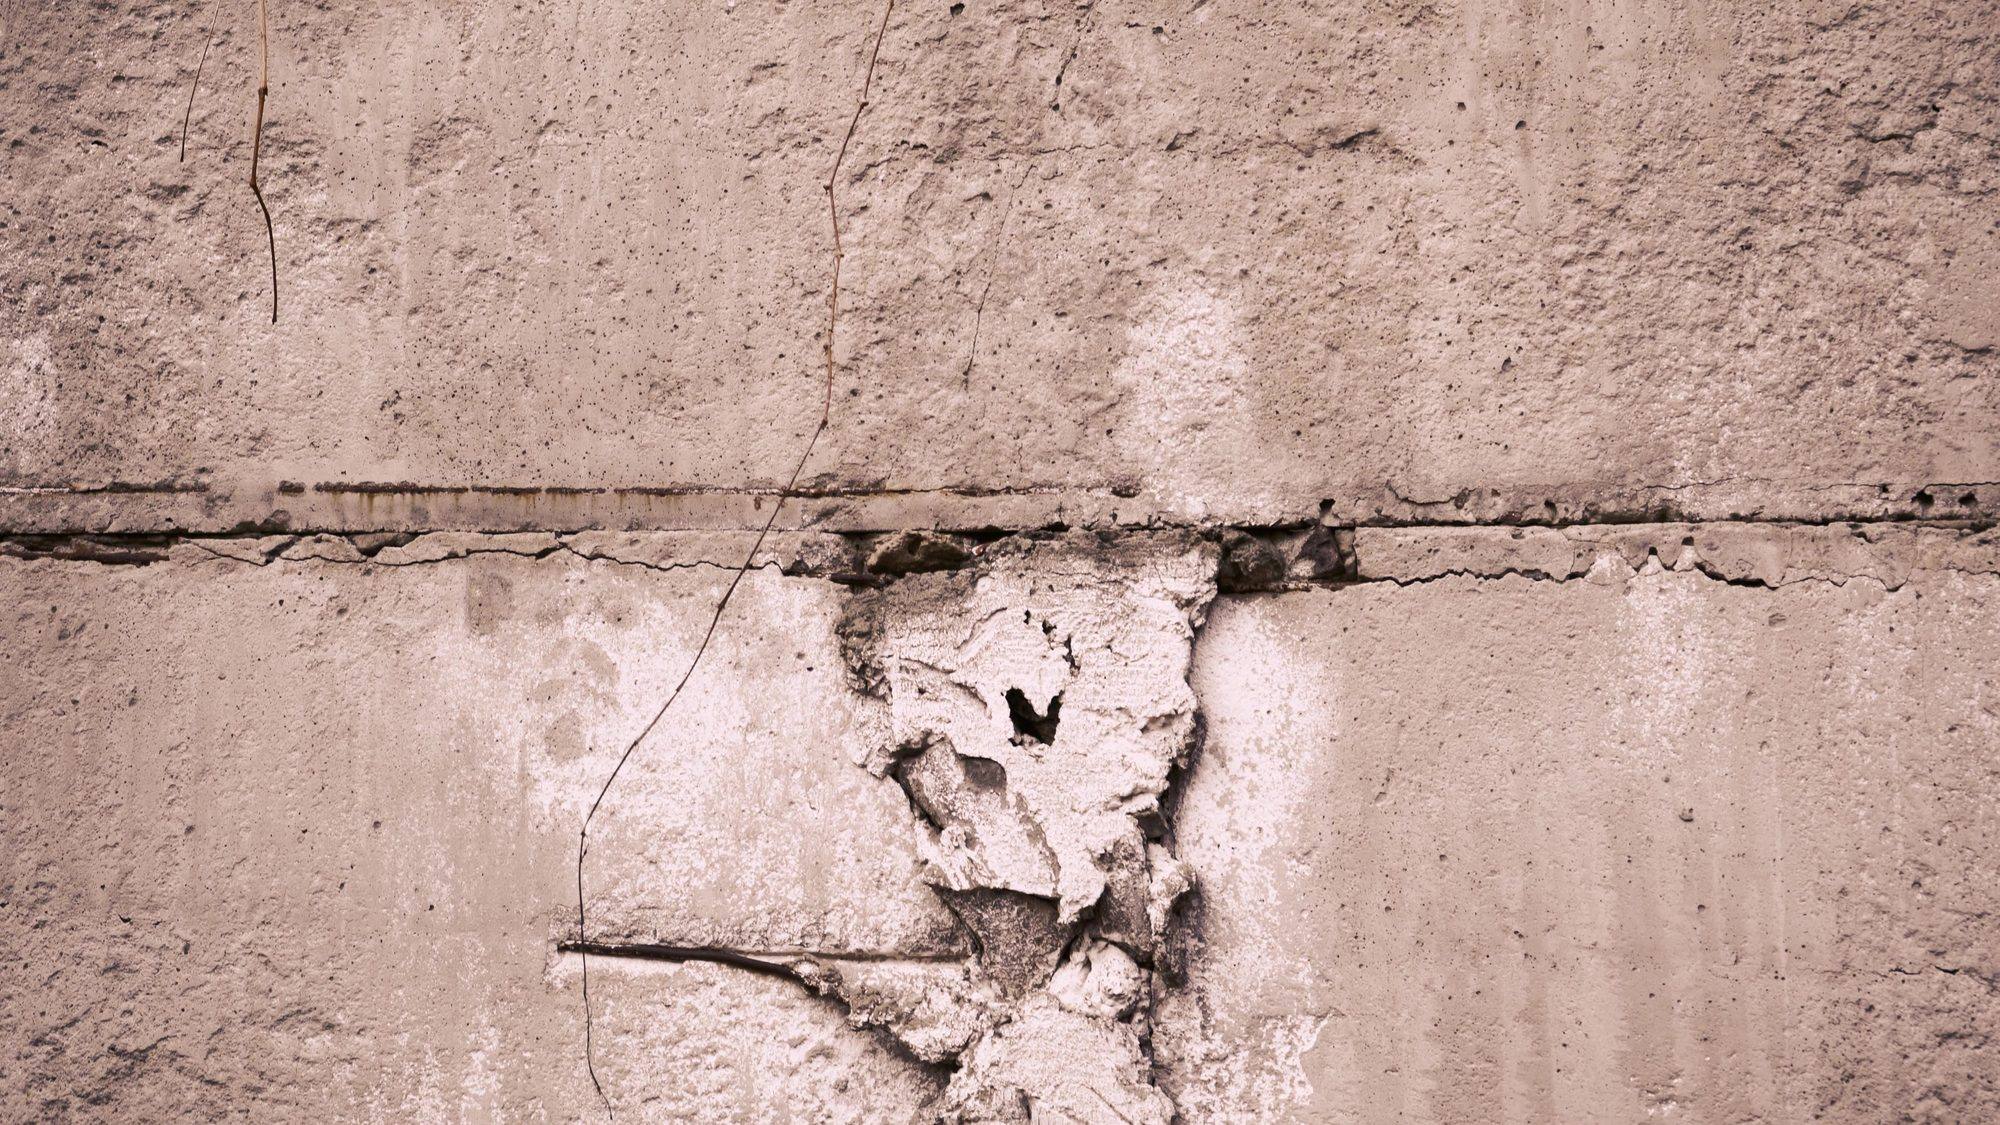
Once you’ve found a crack, the real question isn’t how bad it looks but why and when it happened. That’s a structural question first and an insurance question second, so this guide draws on the evaluations of our structural contributor, Daniel Mercer.
What is usually excluded, and what can be covered
| Cause | Typical result | Why |
|---|---|---|
| Long-term settlement | Usually excluded | Falls under earth movement or settling exclusions |
| Expansive soil (shrinking and swelling) | Usually excluded | Earth movement exclusion |
| Poor drainage over years | Usually excluded | Gradual damage, often treated as maintenance |
| Vehicle impact | Potentially covered | Sudden, dated, with a clear cause |
| Sudden leak under the slab | The water damage can be covered; the pipe and earlier settlement may not be | Accidental discharge is separated from progressive movement |
| Collapse | Depends on the policy’s collapse wording and covered causes | Cracks or a risk of future failure aren’t collapse |
Slab leaks are the tricky row. A broken pipe can be a covered accidental discharge, while the ground movement it causes, or movement that was already there, may fall under the exclusion. The insurer will assess each part under the policy.
From the field: three evaluations
These are real evaluations by Daniel, described with only the state to protect the owners.
Settlement or sudden damage: how it gets assessed
When Daniel evaluates foundation damage that may end up in a claim, he looks at the whole picture rather than any single crack:
- The pattern of the cracks and whether the sides have shifted relative to each other
- Floor levels and any distortion in walls, frames and joints
- Older photos of the house, if the owner has them
- Gutters, downspouts, grading and soil conditions around the house
- Any recent work nearby, on the house or next door
If you can’t tell whether movement is still happening, monitoring the house with instruments over time can settle it. And you can’t tell how old a crack is from its width.
When to hire your own engineer
An independent structural evaluation is worth paying for when walls have moved noticeably, a wall is bowing, you’re unsure the house is stable, or you and the insurer disagree significantly about the cause or the repair. If there’s an immediate risk, make the area safe first and deal with the insurance later. An engineer’s report helps your claim, but it doesn’t guarantee coverage.
Separate coverages worth knowing
None of these is general foundation coverage. Each answers one specific cause.
- Mine subsidence. In parts of Pennsylvania and Ohio, ground movement from old underground mines is a real risk, and homeowners policies exclude it under earth movement. Both states run their own programs. Pennsylvania’s Mine Subsidence Insurance program is offered through the Department of Environmental Protection and has paid more than $30 million in claims since 1961. In Ohio, the coverage is mandatory in 26 counties and optional in 11, and pays up to $300,000 or the dwelling’s insured amount, whichever is less.
- Earthquake. Sold separately or as an endorsement; not part of a standard homeowners policy.
- Flood. A separate flood policy, NFIP or private. Damage caused by a qualifying flood may fall under this policy, subject to its terms. Not all erosion, groundwater or foundation movement counts as flood damage.
- Service Line Coverage. Can cover certain buried utility lines on your property, such as water or sewer lines. It’s about the pipe, not the foundation.
- Equipment Breakdown. Covers internal failure of covered equipment, not structural damage.
If you’re dealing with settlement rather than an insurance question, our foundation settling guide explains the causes and repair options, and the repair cost guide covers what the work usually costs.
Coverage depends on your policy wording and your state. Confirm with your insurer or agent before making a decision.
Structural information reviewed for technical accuracy by Daniel Mercer. This content is educational and is not a substitute for an on-site evaluation by a licensed professional engineer.
Insurance information reviewed for accuracy by Nathaniel Calderbrook. This is general information, not a coverage decision: your policy wording and your state decide what is covered.
Who wrote this guide
Written by
Licensed contractor in Virginia who specializes in moisture, water, mold and radon.
- Five IICRC certifications, including Building Moisture Inspection and Mold Remediation Specialist
- Virginia contractor license, Residential Building Contractor (RBC) class
- NRPP certified Radon Measurement Professional (2018) and Radon Mitigation Specialist (2020)
- EPA RRP Certified Renovator (lead-safe renovation)
Structural review
Daniel Mercer, Structural Contributor
Reviews the structural information in this guide for technical accuracy.
- Civil engineering graduate, Virginia Tech (2008)
- More than 17 years evaluating existing homes in Virginia
Insurance review
Nathaniel Calderbrook, Home Insurance & Claims Contributor
Reviews the insurance information in this guide for accuracy.
- Licensed Property & Casualty Insurance Producer in Virginia, Maryland and Pennsylvania
- 17 years in homeowners insurance, with a focus on water damage and structural claims
- Independent agent: earns commissions from insurers. We don’t recommend insurers or send readers to any agent
Below the Sill is independent and educational. We don’t provide inspections, engineering or repair services, contractor referrals or estimates.
Share this guide
All 5 guides in Insurance & claims
Insurance & claims topic page- 01Flooded basement insurance
- 02Mold and insurance
- 03Water backup coverage
- 04Foundation damage and insurance (you’re here)
- 05Water damage claims
A seasonal check, by email
Four emails a year, before each season changes: what to look at in your basement, crawl space and yard, and the guides we’ve published since the last one.
Sources
- Pennsylvania Department of Environmental Protection, Mine Subsidence Insurance (opens in a new tab). Checked October 2026.
- Ohio Department of Natural Resources, Mine Subsidence Insurance (opens in a new tab). Checked October 2026.
Field cases come from Daniel Mercer’s own evaluations; each names only the state to keep the owners anonymous. The Ohio figures come from the Ohio Department of Natural Resources. Below the Sill doesn’t sell insurance, recommend insurers or send customers to repair companies.